 If you searched portugal golden visa tax implications for us citizens, you want a clear map of what changes after you invest, and what does not. A Portugal Golden Visa is an immigration residency path. It is not a US tax exit, and it does not automatically make you a Portuguese tax resident.
Plan-B Outbound Migration Consultancy is a Beverly Hills practice (since 2009) led by founding partner Calvin S. Mazlumyan, Esq., a California licensed immigration attorney. The firm helps US and Canadian families coordinate Golden Visa strategy and document concierge work. Tax filings still belong with a cross-border CPA or tax attorney.
This guide separates immigration residency from tax residency, covers the US reporting themes Americans meet most often (PFIC, FBAR, FATCA), and outlines a practical checklist before any fund subscription. Nothing here is legal or tax advice. No advisor can guarantee government approval outcomes.
Does a Portugal Golden Visa change US tax status?
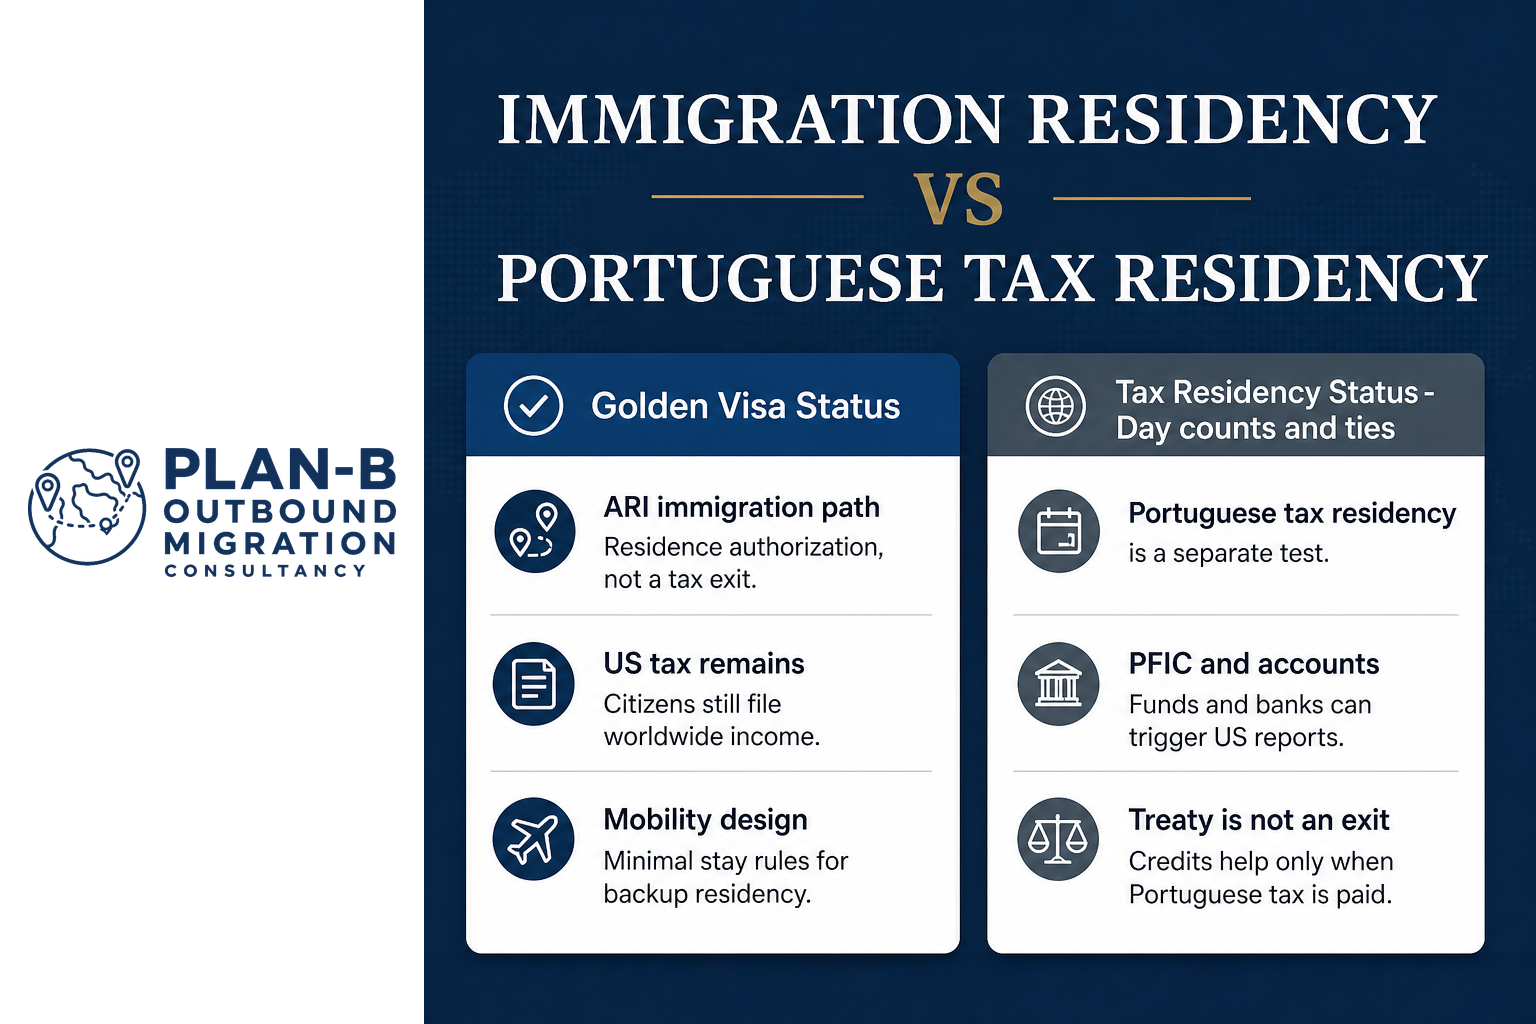
No. US citizens remain US tax persons on worldwide income whether or not they hold a Portugal Golden Visa. Portuguese immigration residency does not switch off Form 1040 filing or citizenship-based US taxation.
The Golden Visa is an ARI-style residence authorization under Portuguese immigration rules. Confirm current program mechanics on the AIMA ARI portal. Program thresholds and stay rules change. Confirm facts before you model tax outcomes.
What usually stays true for Americans:
- You keep filing a US federal return on worldwide income
- Portuguese residency status is a separate Portuguese-law analysis
- Opening Portuguese accounts can trigger US information reporting once thresholds are met
- Fund investments often create PFIC reporting on the US side
Plan-B can help sequence immigration documents and NIF or banking introductions. Independent US tax counsel should review fund subscriptions, elections, and reporting calendars before capital moves.
What is the difference between Golden Visa residency and Portuguese tax residency?
Golden Visa residency is immigration status. Portuguese tax residency is a tax-law status that depends on day counts, ties, and Portuguese rules. You can hold a Golden Visa and still remain a non-tax-resident of Portugal if your facts support that position.
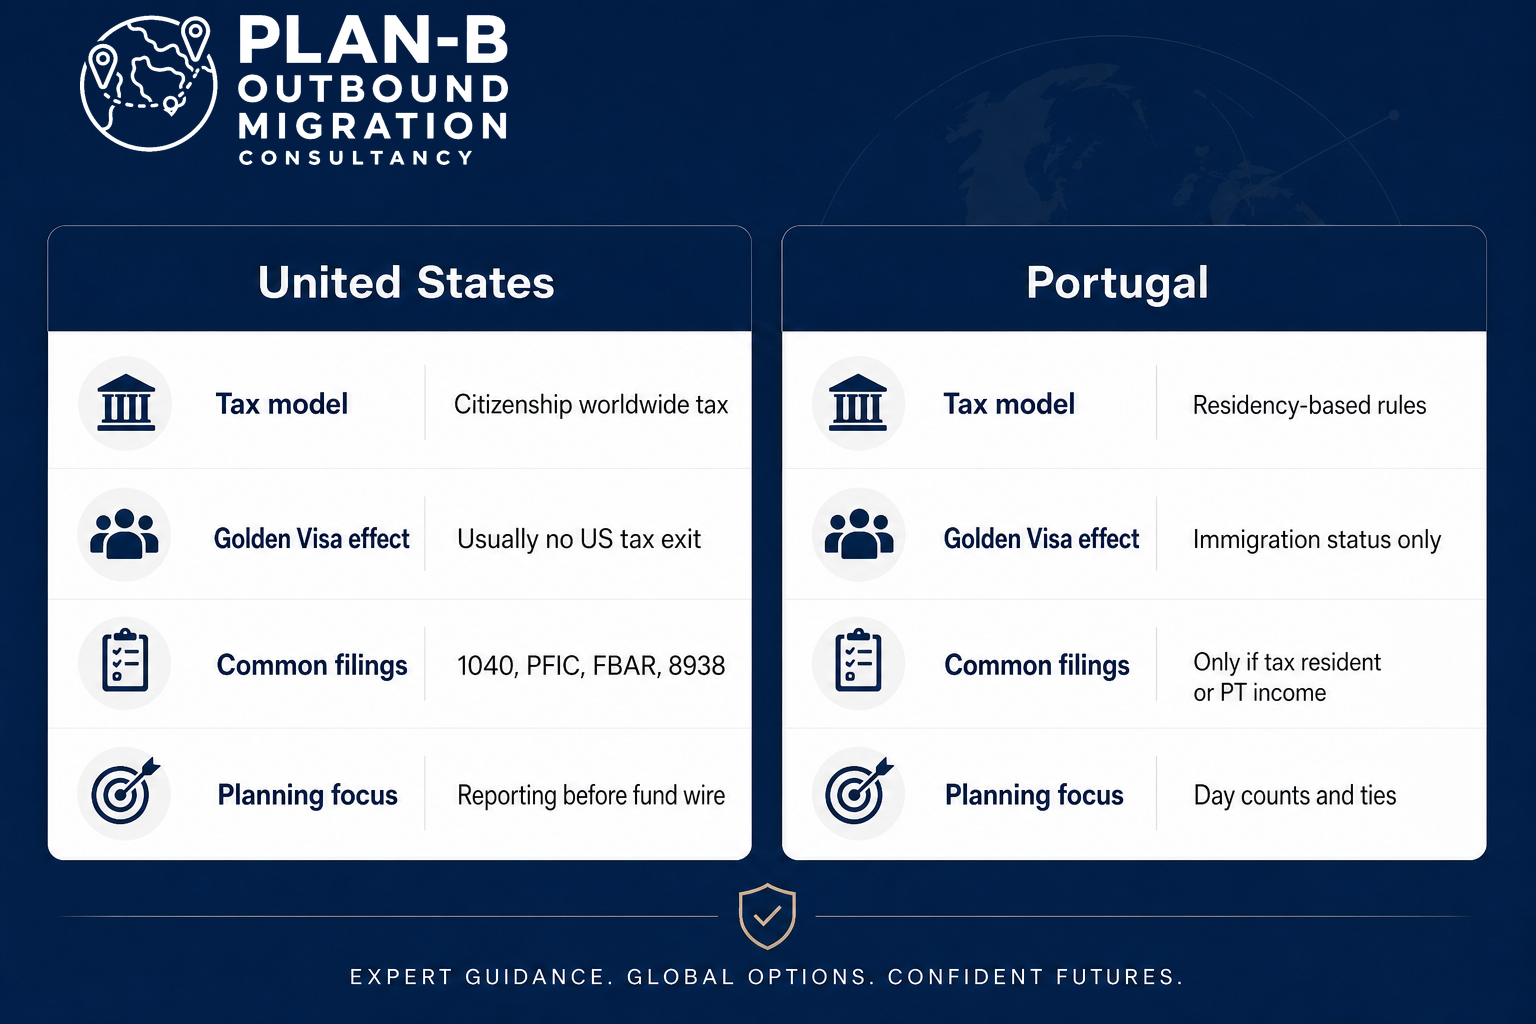
| Topic | United States | Portugal |
|---|---|---|
| Core taxing model | Citizenship-based worldwide taxation for US citizens | Residency-based rules for Portuguese tax residents |
| What Golden Visa changes | Usually nothing about citizenship tax status | Immigration permission to reside, not automatic tax residency |
| Typical US filings | Form 1040 plus foreign account and asset reports when thresholds apply | N/A until Portuguese tax residency or Portuguese-source income arises |
| Common planning mistake | Assuming EU residency ends US tax | Assuming immigration days equal tax residency days |
Minimal Golden Visa physical-presence rules are designed for mobility, not full-time relocation. Extending stays, renting long term, or moving family life to Portugal can change the Portuguese tax analysis. Get written advice before you treat "non-resident" as permanent.
For program context, see the Portugal Golden Visa 2025 overview and the benefits guide for US clients.
What US reporting issues do Golden Visa fund investors face?
Most US investors in Portuguese Golden Visa funds should plan for PFIC analysis, annual Form 8621 issues, FBAR reporting for foreign accounts, and FATCA Form 8938 when asset thresholds are met. These are US rules that sit on top of Portuguese immigration paperwork.
PFIC and Form 8621
Many Portuguese investment funds are treated as Passive Foreign Investment Companies (PFICs) for US tax purposes. PFIC status can mean special elections and annual reporting. See the IRS page for Form 8621. Ask your CPA whether a Qualified Electing Fund (QEF) or another election is available, and whether the fund can supply the annual statements you need.
PFIC planning is not optional marketing fine print. It can affect timing of income recognition and cash-flow needs even when the fund distributes little cash.
FBAR (FinCEN Form 114)
If the aggregate value of your foreign financial accounts exceeds the FBAR threshold at any time during the year, you may need to file FinCEN Form 114. Start with FinCEN's FBAR overview. Portuguese bank accounts used for fund subscription often sit inside this analysis.
FATCA Form 8938
FATCA Form 8938 can apply when specified foreign financial assets exceed IRS thresholds. Thresholds differ for taxpayers living in the US versus abroad. See the IRS page for Form 8938 and the broader FATCA overview.
FBAR and Form 8938 are information reports with different rules. The same account can appear in more than one report without meaning you are taxed twice on the same dollars.
How do double tax and treaty themes usually work?
The United States and Portugal have an income tax treaty framework, and US foreign tax credits can reduce double taxation when Portuguese tax is actually paid. Treaty and credit mechanics are fact-specific. They do not erase PFIC classification or information-reporting duties.
Useful official starting points:
- US Treasury tax treaties materials
- IRS FATCA and Form 8938 guidance linked above
- Industry policy monitoring via IMI Daily for investment-migration changes that can alter timing assumptions
Do not assume "no Portuguese tax bill" means "no US compliance work." For many Golden Visa holders who remain US-based most of the year, the heavier lift is US reporting around the fund and foreign accounts.
What about NHR, IFICI, and relocation tax marketing?
Portugal's older Non-Habitual Resident (NHR) regime is closed to new applicants. Successor or alternative regimes such as IFICI are narrower and activity-based. None of them remove US citizenship-based taxation.
Marketing pages sometimes imply that Portuguese tax incentives solve the American tax problem. They do not. A Portuguese incentive may change Portuguese tax on qualifying Portuguese income or certain foreign-source items for qualifying residents. US worldwide taxation and PFIC rules remain.
If relocation tax benefits matter to you, settle eligibility with Portuguese and US advisors before you move days, family, or business activity to Portugal. Immigration counsel and tax counsel should talk to each other, not work in silos.
What checklist should Americans complete before investing?
Complete a tax and reporting checklist before you subscribe to a fund or wire capital: separate immigration from tax residency, review PFIC elections with a US CPA, map FBAR and FATCA thresholds, and model cash flow for possible phantom income. Do this before marketing timelines push you into a wire date.
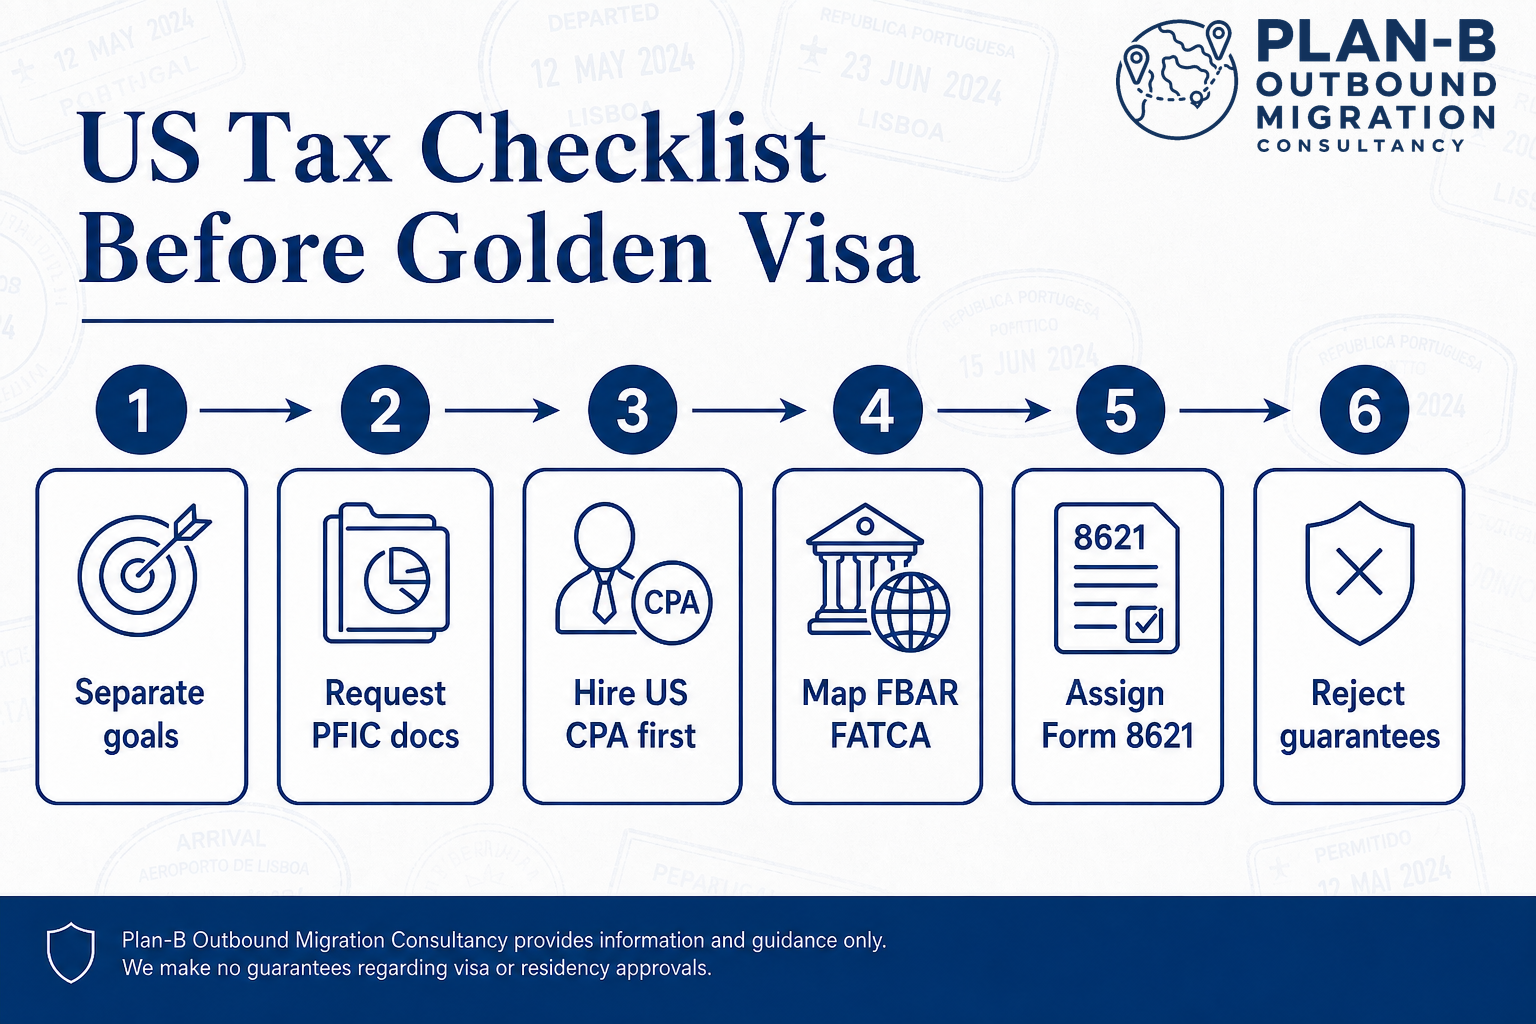
- Separate goals: immigration backup residency versus Portuguese tax residency versus full relocation
- Ask every fund manager for US investor documents and PFIC annual statement support
- Engage a US cross-border CPA before subscription documents are signed
- Map Portuguese bank accounts against FBAR and Form 8938 thresholds
- Confirm who prepares Form 8621 each year and who keeps the fund statements
- Reject guaranteed approval language and pressure to wire before written immigration and tax scope (USCIS scam diligence mindset)
Plan-B publishes a complimentary consultation on outboundmigration.com for immigration scoping. Bring your tax advisor into the same timeline.
What questions should you ask advisors and CPAs?
Ask immigration advisors what they do not handle on tax, and ask CPAs how they will treat the specific fund, elections, and reporting calendar. Clear ownership prevents gaps between AIMA filings and IRS forms.
Ask your immigration advisor:
- Who coordinates NIF and Portuguese banking introductions?
- What is excluded from fees (tax advice, securities advice, fund selection liability)?
- How do document deadlines interact with fund subscription timing?
Ask your US tax advisor:
- Is this fund a PFIC, and which election is recommended in year one?
- What phantom-income cash buffer should we plan for?
- Which accounts trigger FBAR or Form 8938 in our filing status?
- How does any Portuguese tax paid interact with foreign tax credits?
If you are still deciding whether to leave the US base at all, start with what US citizens need to know before moving abroad.
FAQ
Do US citizens pay Portuguese tax just for holding a Golden Visa?
Not automatically. Immigration residency and Portuguese tax residency are different. Many Golden Visa holders stay below Portuguese tax-residency triggers, but day counts and personal ties matter. Confirm with Portuguese counsel.
Does the Golden Visa end US tax filing?
No. US citizens file on worldwide income regardless of foreign residency permits.
Are Portugal Golden Visa funds PFICs for US investors?
Often yes. Treat PFIC analysis as a default planning assumption until your CPA confirms otherwise for the specific vehicle.
Is NHR still available for new US applicants?
The classic NHR regime is closed to new applicants. Newer or successor regimes are narrower. None replace US tax compliance.
Can Plan-B prepare my US tax return?
Plan-B is an outbound migration consultancy focused on residency and citizenship planning. US tax returns and PFIC elections belong with a licensed CPA or tax attorney. Plan-B can help you sequence immigration steps so tax advisors have time to work before wires.
What is the biggest tax mistake Americans make on this keyword?
Assuming the Golden Visa is a tax product. It is an immigration product with tax side effects. Budget for US reporting before you chase residency timelines.
Next step
If you are a US citizen modeling portugal golden visa tax implications, shortlist immigration scope and tax scope as two workstreams, then book both before any capital transfer.
Plan-B Outbound Migration Consultancy offers a complimentary 30-minute consultation and publishes guides on the Plan-B blogs hub.
Disclaimer: General information only, not legal or tax advice. Immigration and tax rules change. Confirm all requirements with licensed US and Portuguese professionals and official government sources before applying or investing. No outcome is guaranteed.